

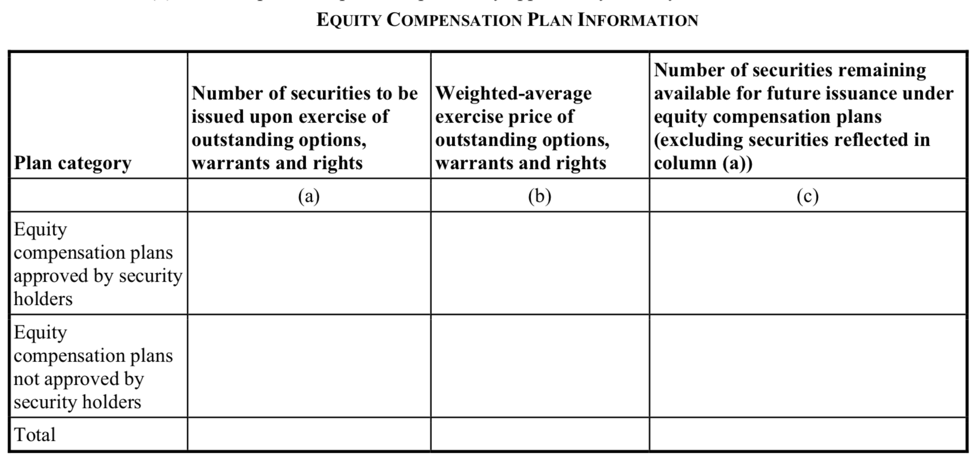
From its inception, this table required by S-K Item 201(d) has created confusion:
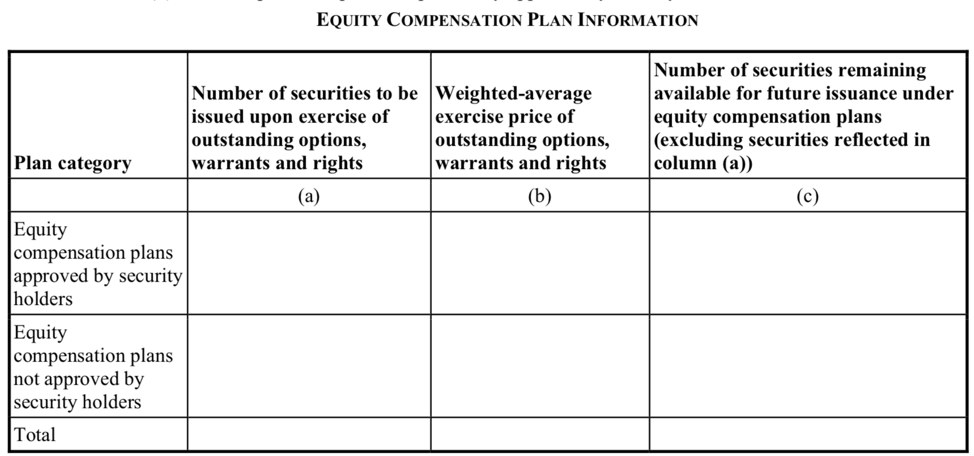
The table is clearly included in S-K Item 201. The instructions to Item 5 in Form 10-K clearly require that the information required by S-K item 201 should be included in Item 5. Here is a relevant excerpt:
Item 5. Market for Registrant’s Common Equity, Related Stockholder Matters and Issuer Purchases of Equity Securities.
(a) Furnish the information required by Item 201 of Regulation S-K (17 CFR 229.201) …….
The problem the SEC created when they first required this table was that they also added the table to the instructions for Item 12 in Form 10-K:
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
Furnish the information required by Item 201(d) of Regulation S-K (§ 229.201(d) of this chapter) and Item 403 of Regulation S-K (§ 229.403 of this chapter).
This created what turned out to be enough confusion about where to place the table (Item 5 or Item 12) in Form 10-K that the American Bar Association asked the SEC to clarify the situation. The SEC did this, issuing first a letter to the ABAand then a Compliance and Disclosure Interpretation stating the table should be in Item 12, not Item 5. (It would appear they sort of forgot to update the instructions to Item 5…)
Here is the relevant C&DI:
Question 106.01
Question: Is the Item 201(d) disclosure required in Part II of Form 10-K, given that Item 5 of Form 10-K indicates that the registrant is required to furnish the information required under Item 201, or should the Item 201(d) disclosure be included (or incorporated by reference) in Part III of Form 10-K given that Item 12 indicates that the registrant is required to furnish the information required under Item 201(d)?
Answer: The Item 201(d) disclosure should be included in Part III, Item 12 of Form 10-K. An issuer may rely on General Instruction G.3 to Form 10-K to incorporate by reference the Item 201(d) disclosure from its proxy statement or information statement, even if the issuer did not submit a compensation plan for security holder action at its annual meeting of security holders. SeeAmerican Bar Association (Jan. 30, 2004). [Mar. 13, 2007]
This table was also required in Schedule 14A for the proxy statement.
When the SEC finalized its Disclosure Update and Simplification rule in August, they recognized that most of the information required by the table is now in the notes to the financial statements. In addition, one of the key disclosures in the table, plans approved by shareholders and plans not approved by shareholders, is much less relevant today as the major security exchanges now require essentially all plans to be approved by shareholders.
Because of this the SEC has made two changes for this table.
First, they have deleted the requirement for the table in the proxy statement by deleting this language from Schedule 14A, as you can find on page A152 of the SEC’s Demonstration Version of the rule:
Item 10. Compensation Plans.
***
(c) Information regarding plans and other arrangements not subject to security holder action. Furnish the information required by Item 201(d) of Regulation S-K (§229.201(d) of this chapter).
The instruction to this rule was also deleted.
And, just to make this even more detailed, theDisclosure Update and Simplification rule also removes the requirement to disclosure this table from Item 12 in Form 10-K(see page A 184 of the demonstration version):
Item 12. Security Ownership of Certain Beneficial Owners and Management and Related Stockholder Matters.
Furnish the information required by Item 201(d) of Regulation S-K (§229.201(d) of this chapter) and byItem 403 of Regulation S-K (§229.403 of this chapter).
The bottom line: the table should now be included in Item 5 in Form 10-K.
This is also one of the issues the SEC asked the FASB to address and so more could come later in the notes to the financial statements.
As always, your thoughts and comments are welcome!