

On June 25, 2015, the U.S. Supreme Court issued its decision in King v. Burwell, ruling that Section 36B of the Patient Protection and Affordable Care Act (“ACA”) authorizes insurance exchanges run by the federal government to issue tax subsidies like their state-run counterparts. The 6-3 decision was authored by Chief Justice Roberts, an appointee of President George W. Bush.
The case involved whether Section 36B of the ACA permits only state-run exchanges to issue tax subsidies to qualifying purchasers of coverage. That Section defines “premium assistance amount” in part by referring to insurance plans that are enrolled in “an Exchange established by the State.” The absence of any reference to federal exchanges in these portions of Section 36B led opponents of the Act to argue that only state-run exchanges have the power to issue ACA tax subsidies. Since only 16 states (plus the District of Columbia) elected to run their own exchanges, the opponents’ position, if adopted, could have made ACA tax subsidies unavailable to residents of 34 states (including Pennsylvania) – and may have rendered the “individual mandate” penalty unenforceable in those states.
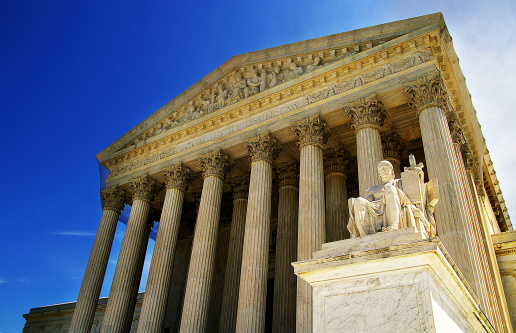 The preliminary issue facing the Court was whether the Act, and specifically Section 36B, was ambiguous with respect to its use of the phrase “Exchange established by the State.” Acknowledging that the ACA is replete with “more than a few examples of inartful drafting,” Justice Roberts recited a number of passages in the ACA in which Congress blurred the distinction between state-run and federal exchanges. Given this ambiguity, the Court looked to the greater context of the Act and legislative intent. Finding ample provisions in the Act to support the notion of subsidies being issued by all exchanges, the Court ruled that Congress intended the Act to be interpreted to allow for such subsidies. Otherwise, the Court surmised, the individual insurance markets in states with federal exchanges may experience a “death spiral” – a result that the ACA was intended to prevent.
In sum, the Court found that the opponents of the law were arguing that “Congress made the viability of the entire Affordable Care Act turn on the ultimate ancillary provision: a sub-sub-sub section of the Tax Code. We doubt that is what Congress meant to do.”
Employers with 50-99 employees are expected to comply with the “pay or play” provisions of the Act in 2016. For those employers that have already begun to plan to comply, today’s decision is an endorsement to “carry on.” For employers that have delayed planning in hopes that the Supreme Court would derail the ACA, it is now time to catch-up.
If you have any questions regarding this article or the ACA, please contact any member of our Labor and Employment Practice Group.