


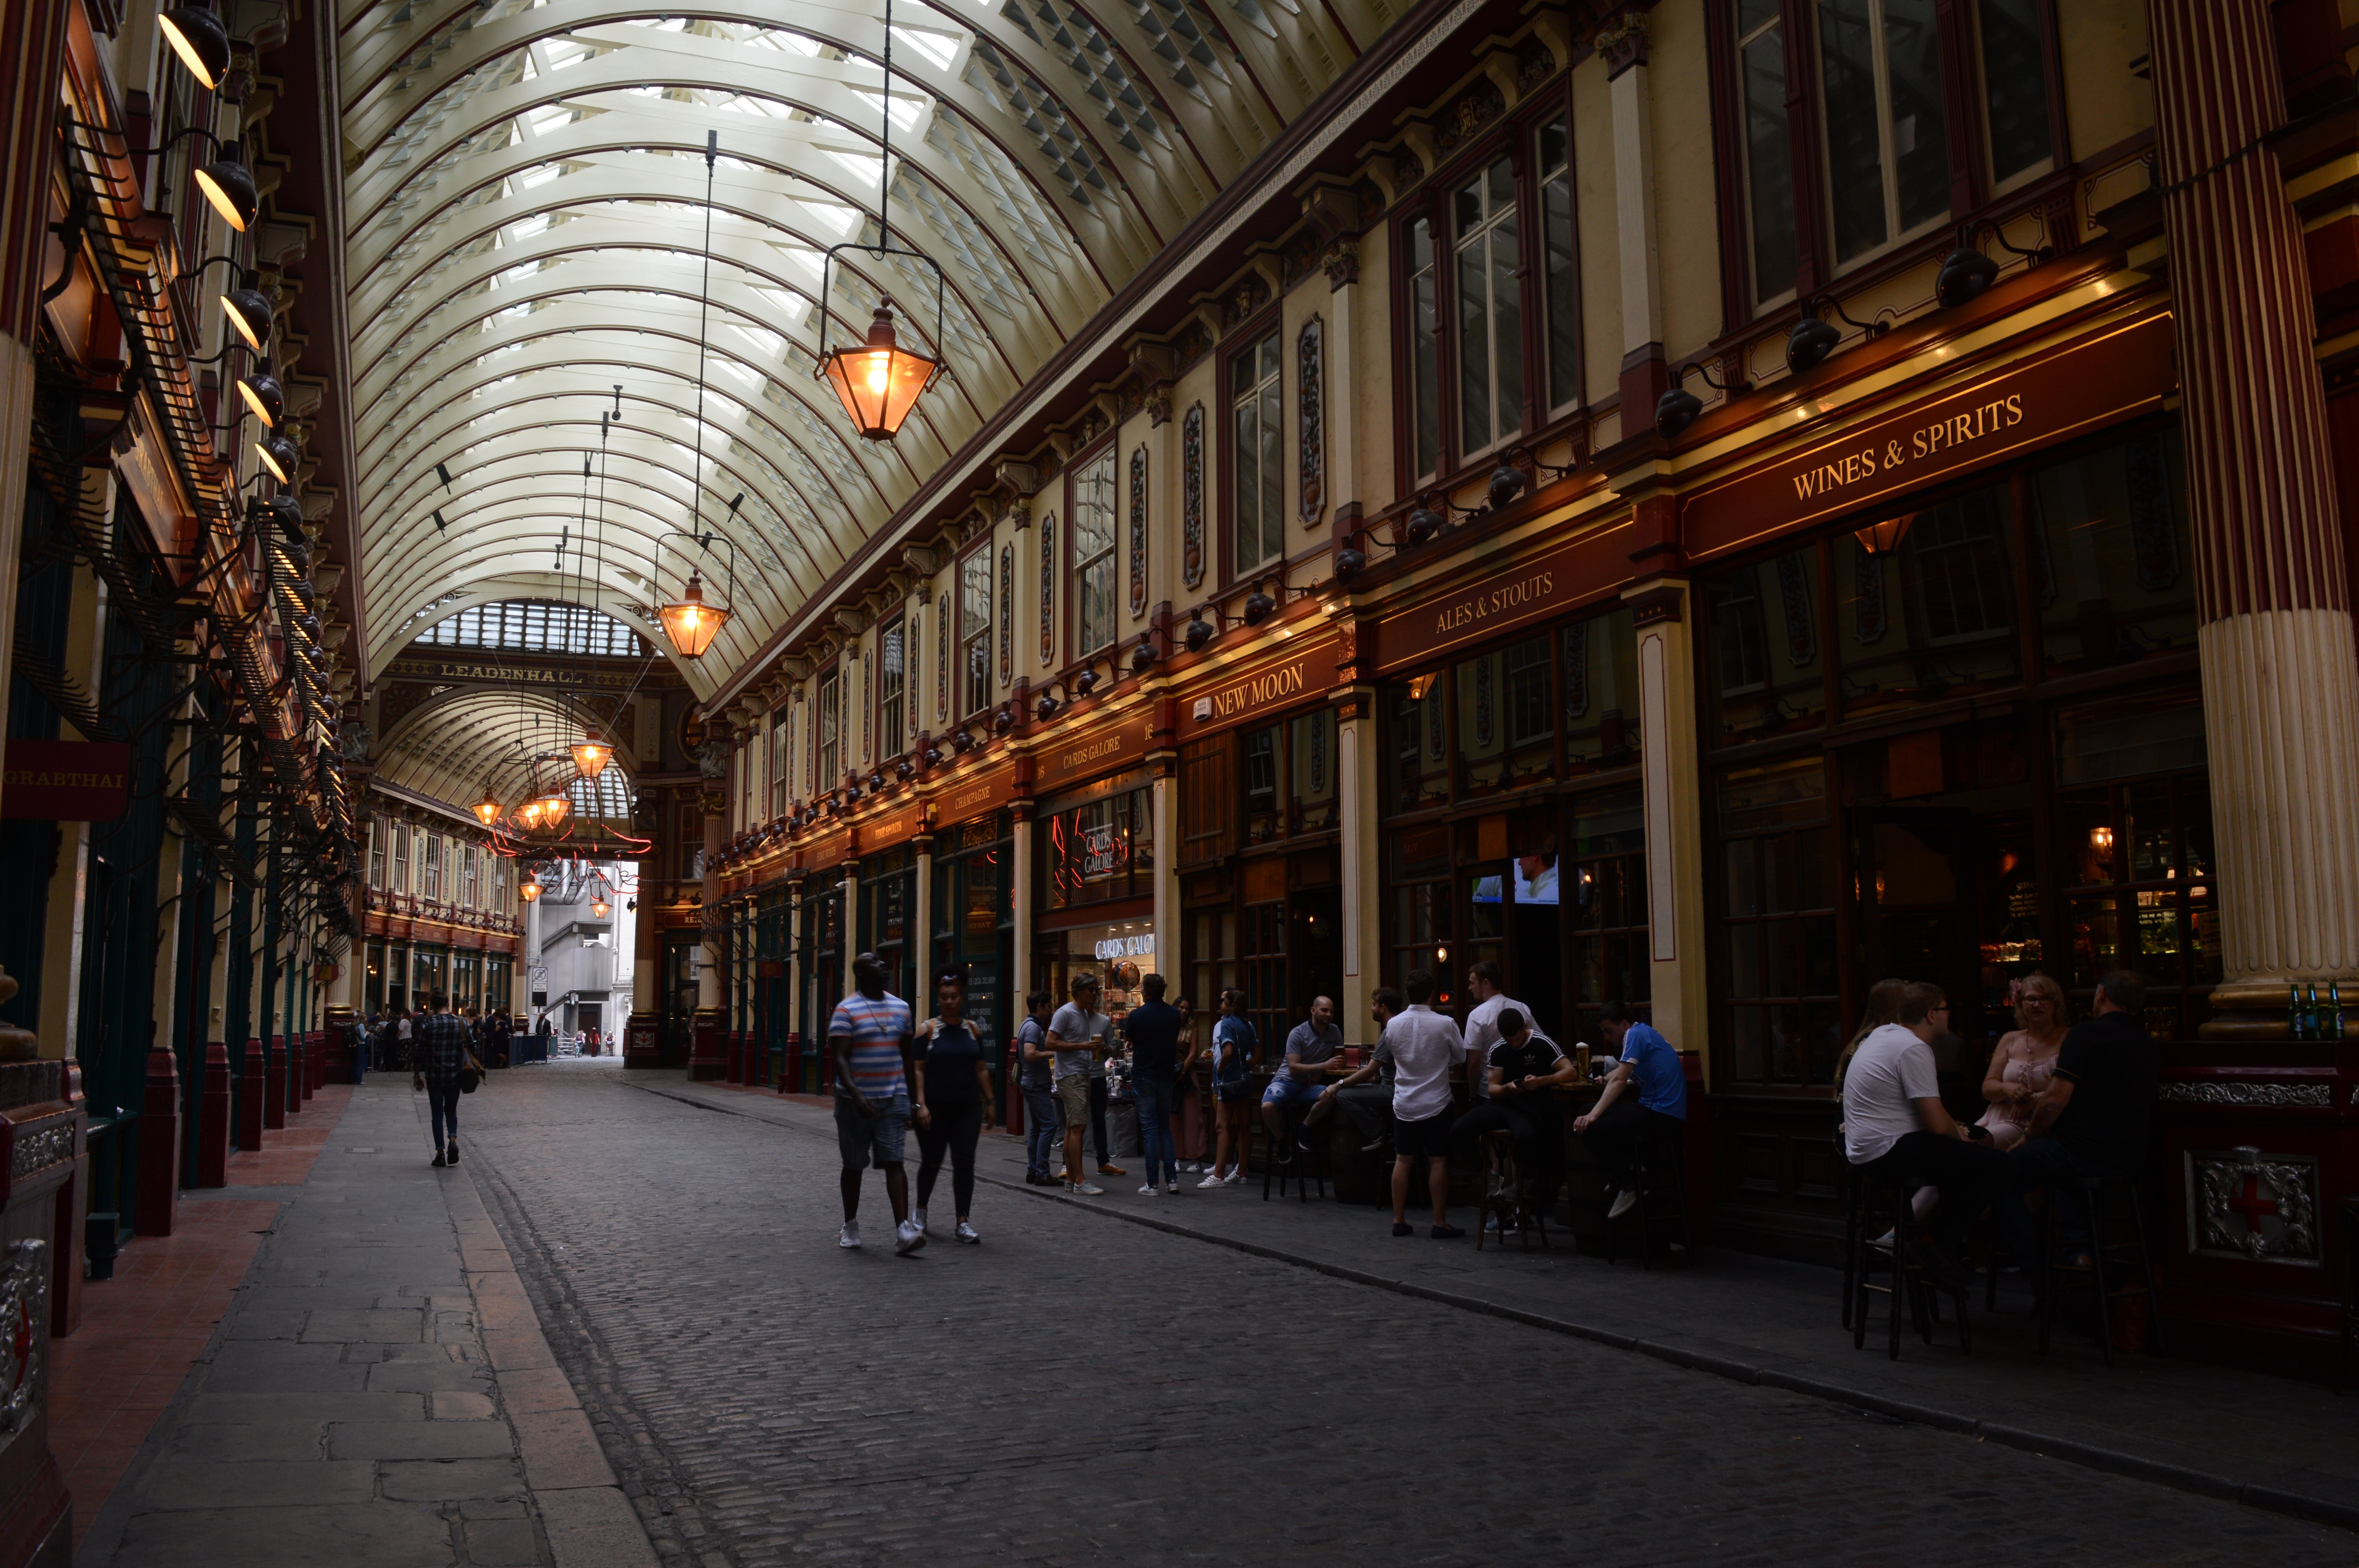
Welcome to Leadenhall Market, alleged and acclaimed as the inspiration for Diagon Alley in J.K. Rowling’s Harry Potter series. In the heart of the City, nestled between the Walkie Talkie and the Gherkin, sits London’s answer to the Galleria Vittorio Emanuele II. It’s charming, and unsurprising that it inspired Rowling to create her magical high street, hidden in central London. In Rowling’s world, unicorns are elusive, magical creatures. In the City of London, they are FinTech giants, some growing exponentially, some at the IPO stage of development as they go public. But, are we ready for the unicorns? After the flops of 2019, what’s the current situation and what can we expect from 2020?

1. What is a ‘Unicorn’?
My parents are never quite sure if I’m serious when I come out with terms like ‘unicorn’ when talking about work. Fear not, these are real corporate creatures which have mastered growing, though not yet floating.
Familiar unicorns include Air BnB, Pintrest, Uber (though admittedly this is no longer a private company), Lyft (similarly, this went public last year) and Deliveroo. Some of the first generation of unicorns we might pick out as Alphabet, Google and Facebook.
2. What progress have we seen from unicorns already?
If you kept up with 2019, you will have seen the first-quarter excitement at the prospect of Unicorns like Air BnB, Pintrest, Uber and Lyft launching their IPOs (i.e. making the transition from private to public companies).
March 2019 saw Lyft take to the capital markets skies in an attempt to float. Huge
Onlookers watched with
WeWork
In September 2019 it was the home-fitness spin-revolution Peloton’s turn to go public. Though shares
3. How can we understand these trends?
Unicorns are usually tech-based start-ups. They often have very few tangible assets on their balance sheets and may exhibit heavy losses. The business model of many of these start-ups is dominance. Take the example of Amazon, which operated at a loss for years before investors saw a return on capital, waiting as the corporation undercut competitors to develop a market so broad and products so cheap that many of us do not think twice about using such an efficient, affordable service. It still weathers heavy losses today, but has achieved dominance across a number of sectors. Consider Facebook and Uber, though these corporations have offices, computers and personnel on their balance sheets, most of their value is tied up in intangibles such as technological innovations and goodwill. How should these be valued?
This is one of the difficulties unicorns have faced. There is yet to be an accepted objective valuation of data and innovation in business. These are prospective potential gains, there is no guarantee that the data collected and stored by these unicorns can be converted into value. Similarly, there is no guarantee that research and development will lead to infallible innovations which drawn in profit. In short, unicorns are flighty, unpredictable creatures.
High demand for unicorn stock has fuelled high valuations which have often be rejected by markets. Whilst venture capitalists are willing to take a punt on high-risk businesses which reap losses before bounty, shareholders are often far more risk-averse. Venture capitalists willingly search out seeds of innovation and data in businesses, which may germinate to produce blossoming profits. Shareholders want well-stocked storehouses as a buffer against fluctuating market conditions.
Valuation is not the only barrier to unicorn entry into public markets. Often innovative tech start-ups, the legality of unicorns has often been opaque. Uber is currently facing
Do these different investor interests, and unique characteristics of unicorns render public markets impenetrable?
4. What can we expect from 2020?
There remains a herd of unicorns ready to
Unicorns are not yet populating the skies of public markets. If market conditions change to weather the risk which characterises these corporate creatures, accepting higher-risk and long-term investment, perhaps this can change. By nature, unicorns are fast-developing beasts, likely to undertake work which falls outside the clear definitions of law. If legal certainty and commercial stability (factors likely only to develop with time) can be achieved, perhaps we shall soon see more unicorns present in stock exchanges across the globe.
The views expressed in this article are the author’s own and she is solely responsible for them. This article is not intended to be comprehensive, nor to provide legal or financial advice, and its contents should not be relied upon as legal or financial advice, either generally or in relation to any specific transaction. Although the contents of the article are current as at the date of the publication, the information it contains is for informational purposes only, is of a general nature and is not intended to constitute professional advice of any kind. The author accepts no duty of care to any person in relation to this paper and accept no liability for any person’s reliance on this paper. Should you have any questions on issues presented here or on other areas of law, please seek legal advice independently.