

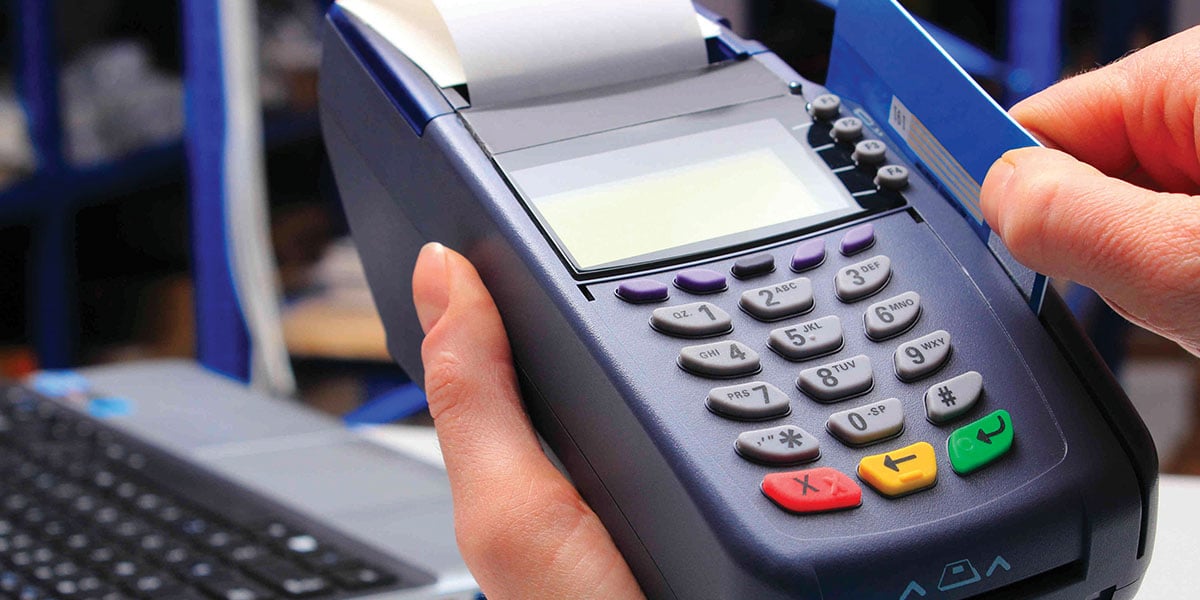
In a February 19 complaint filed in Arizona state court, Texas-based payment processer Switch Commerce LLC argued that multistate cannabis operator Trulieve Cannabis Corp. and its affiliates should be responsible for a $950,000 fine from Visa for their alleged fraudulent use of “cashless ATMs” — not Switch.
Specifically, Switch alleges that the Trulieve defendants fraudulently “mask[ed]” point-of-sale marijuana transactions as ATM cash withdrawals, knowing that card payment network providers like Visa have rules expressly forbidding these types of transactions because marijuana remains illegal federally.
As our team has discussed before, marijuana’s continued status as a Schedule I controlled substance under the federal Controlled Substances Act presents enormous challenges for dispensaries in accessing traditional banking services. This includes the inability to sell products to customers through credit and debit card transactions. In general, banks, card networks, and payment processors do not want the legal risks associated with aiding and abetting transactions involving controlled substances, which is prohibited under federal law. That leaves dispensaries looking for workarounds.
ATMs have been the most common solution. Visit any dispensary today and you are likely to see an ATM somewhere on the property that gives customers ready access to cash to make their purchases. Because the cash could be used for any purpose, any cash withdrawals from such ATMs are not directly linked to marijuana sales. Some dispensaries further mitigate their risk by ensuring that the ATMs are located outside of the licensed marijuana premises entirely.
These traditional ATMs, however, have their drawbacks. For dispensaries, running a cash-only business makes them easy targets for robbery and theft, posing harms to their employees and bottom line. For customers, withdrawing cash is not as convenient as making a single swipe of their card to purchase a product.
This has led some dispensaries to process sales of marijuana products through “cashless ATM” transactions. For example, in its complaint, Switch alleges that the Trulieve merchants use modified ATMs and point-of-sale devices that allow customers and merchants to swipe, tap, or insert cards to process a payment for a marijuana product, but the data sent to the payment processor Switch — including MCC code 6011, which is reserved exclusively for ATM cash withdrawals — makes it seem like the transaction is from an actual ATM for a cash withdrawal. Then, unwittingly, Switch relays this information for further processing through the card network and the relevant banks.
Visa, however, has rules against processing such cashless ATM transactions for marijuana sales and sends “secret customers” to conduct audits of dispensaries’ transactions. Switch says that Visa’s audits of the Trulieve merchants revealed not only the use of cashless ATM transactions to process marijuana product sales, but also some instances where the ATMs where not even in the locations disclosed to Switch. As a result, Visa fined the relevant sponsor bank $950,000, which the sponsor bank passed on and demanded that Switch pay.
Switch’s lawsuit alleges several state law claims, including fraud, negligent misrepresentation, unjust enrichment, pattern of unlawful activity for financial gain, aiding and abetting tortious conduct, and conspiracy. The company seeks damages to be proven at trial and punitive damages as may be awarded by the jury, as well as interest and costs.
Regardless of the outcome, Switch’s lawsuit lays bare the types of banking challenges facing dispensaries. Although several “SAFE Banking Act” bills have been introduced in Congress that would provide protections for federally regulated financial institutions that serve state-sanctioned marijuana businesses, such as H.R. 2891, S. 2860, and S. 1323, these have not yet garnered enough votes for passage. Until then, we expect to continue seeing businesses employ risky workarounds like “cashless ATM” sales.
Our Cannabis Practice provides advice on issues related to applicable federal and state law. Marijuana remains an illegal controlled substance under federal law.