Skip to content

Menu

LexBlog, Inc. logo
NetworkSub-MenuBrowse by SubjectBrowse by PublisherJoin the NetworkGet StartedSubscribeSupportContact
Search
Close

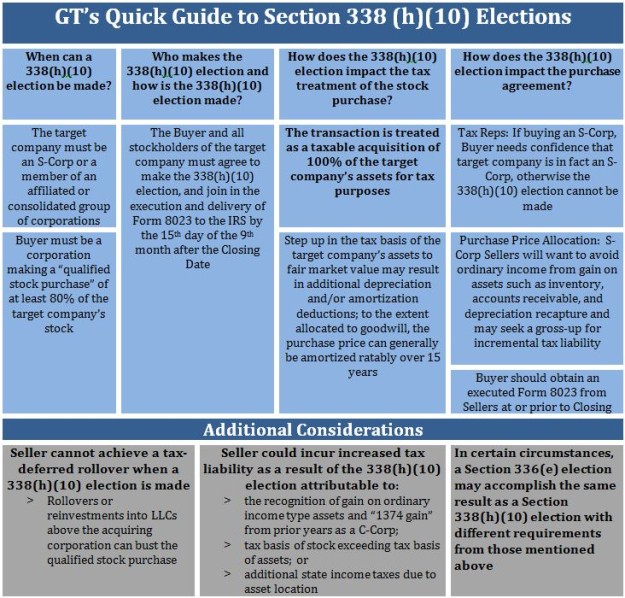
GT’s Quick Guide to Section 338(h)(10) Elections

By Alejandro Ruiz & Noam Lipshitz on July 25, 2016
Email this postTweet this postLike this postShare this post on LinkedIn

Section 338(h)(10) of the Internal Revenue Code can provide significant tax benefits to a buyer of 80% or more of a target corporation. A 338(h)(10) election allows a buyer of stock of an S corporation or a corporation within a consolidated group to treat the transaction as an acquisition of 100% of the assets of the target for tax purposes. The deemed asset sale for tax purposes increases the tax basis of the target’s assets which can significantly reduce the buyer’s future taxable income.

GT’s Quick Guide to Section 338(h)(10) Elections provides you with a quick reference to understanding the 338(h)(10) election, when and how it can be made and its impact on buyers and sellers.
338(h)(10)%20blog%20post

Photo of Noam Lipshitz Noam Lipshitz

Noam Lipshitz focuses his practice on U.S. federal income tax matters, with an emphasis on corporate and partnership transactions. He is experienced handling the tax aspects of mergers and acquisitions, investment partnerships, joint ventures, debt and equity restructurings and securities offerings. His clients…

Noam Lipshitz focuses his practice on U.S. federal income tax matters, with an emphasis on corporate and partnership transactions. He is experienced handling the tax aspects of mergers and acquisitions, investment partnerships, joint ventures, debt and equity restructurings and securities offerings. His clients include private equity funds, venture capital funds, private and public companies, REITs, individuals and tax-exempt organizations.

Read more about Noam LipshitzEmail
Show more Show less
  • Posted in:
    Tax
  • Blog:
    GT Israel Law Blog
  • Organization:
    Greenberg Traurig, LLP
  • Article: View Original Source

Call us at 1-800-913-0988 or email sales@lexblog.com.

Facebook LinkedIn Twitter RSS
The Library at LexBlog
  • About LexBlog
  • The Field We Built
  • Library at LexBlog
  • Our Beliefs
  • Our Team
  • Contact LexBlog
  • Disclaimer
  • Editorial Policy
  • Terms of Service
  • Get Started
  • Publishing Solutions
  • Compass
  • Submit a Request
  • Support Center
  • System Status
Copyright © 2026, LexBlog, Inc. All Rights Reserved.
Law blog design & platform by LexBlog LexBlog Logo