

Skip to content

Menu

LexBlog, Inc. logo
NetworkSub-MenuBrowse by SubjectBrowse by PublisherJoin the NetworkGet StartedSubscribeSupportContact
Search
Close

Applicable Federal Rates and Code Section 7520 Rate for June 2018 – Trending Up

By Carmen Irizarry-Diaz on May 18, 2018
Email this postTweet this postLike this postShare this post on LinkedIn

The applicable federal rates (AFRs) under Internal Revenue Code (Code) Section 1274(d) and the Code Section 7520 rate (7520 rate) for a particular month are published by the Internal Revenue Service (IRS) in a Revenue Ruling that is released around the 18th day of the immediately preceding month. Advance knowledge of the rates for the future month provides a window of opportunity for the quick or delayed implementation of income, gift, and estate-tax planning in response to upward or downward trends. The effective implementation and management of interest-sensitive estate planning techniques also involves numerous other factors in addition to the relevant AFR or 7520 rate, including a client’s particular circumstances and should be undertaken with the advice of competent tax counsel and financial advisors.
The IRS has issued Revenue Ruling 2018-16, which provides the AFRs and 7520 rate for June 2018. Revenue Ruling 2018-16 will be in Internal Revenue Bulletin 2018-23, dated June 4, 2018.

What is the Applicable AFR? The applicable AFR is the minimum acceptable or safe-harbor interest rate that must apply to loans between related parties (intra-family loans) to avoid adverse income or gift-tax consequences — based on the month in which the loan is made, how frequently interest is compounded, and the length or term of the loan.

AFRs Trending Up. AFRs have been trending up, making intra-family loans and installment sales to grantor trusts generally less attractive.

2018 AFRs. The AFRs for January through June 2018 are as follows, in reverse chronological order:
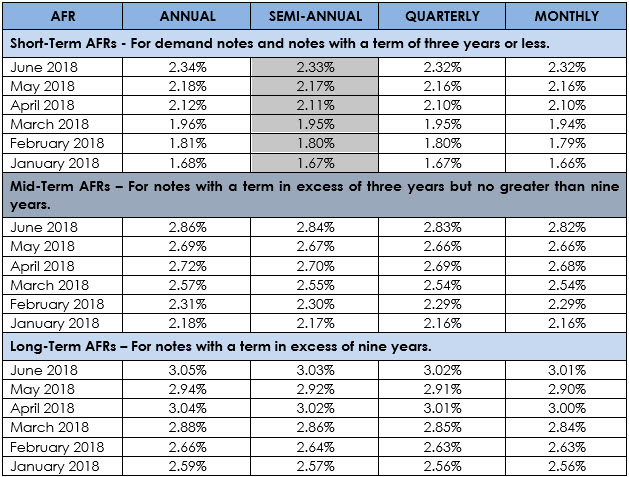
Note that the “blended annual rate” under Code Section 7872(e)(2)(A) may be used to determine the interest on a demand loan (i.e., a loan which can be called in at any time) with a fixed principal amount outstanding for an entire year.

What is the 7520 Rate? The 7520 rate for the month in which a lifetime gift or testamentary transfer occurs is used to determine the gift or estate-tax value of an annuity, an interest for life or for a term of years, or a remainder or a reversionary interest. In the case of a charitable life estate or remainder, however, the 7520 rate for the month in which the lifetime gift or testamentary transfer occurs or a rate for either of the two preceding months may be used to determine its income, gift, or estate-tax value.The 7520 rate is equal to 120 percent of the applicable mid-term rate using semi-annual compounding, adjusting the resulting rate to produce an equivalent yield for annual compounding, and then rounding it to the nearest two-tenths of a percent.

7520 Rate Trending Up. The 7520 rate also has been trending up, making planning techniques like qualified personal residence trusts (QPRTs) and charitable remainder annuity trusts (CRATs) increasingly attractive. Conversely, grantor retained annuity trusts (GRATs) and charitable lead annuity trusts (CLATs) have become generally less attractive as a result of this upward trend.

2018 7520 Rates. The 7520 rates for January through June 2018 are as follows, in reverse chronological order:

Photo of Carmen Irizarry-Diaz Carmen Irizarry-Diaz

Carmen Irizarry-Díaz assists U.S. and international private clients in accomplishing their personal goals for legacy planning and charitable giving. Her practice encompasses all aspects of tax and charitable planning and related instruments and structures – including charitable foundations and trusts – the administration…

Carmen Irizarry-Díaz assists U.S. and international private clients in accomplishing their personal goals for legacy planning and charitable giving. Her practice encompasses all aspects of tax and charitable planning and related instruments and structures – including charitable foundations and trusts – the administration of trusts and estates, and related tax reporting and compliance, including the representation of clients and estates in intra-family controversies as well as before the Internal Revenue Service and other tax authorities. Carmen’s client base includes corporate executives, philanthropists, professionals, families with complex issues (including children with special needs), charitable entities, fiduciaries, and business owners – whom she also counsels on the efficient lifetime and death transfer, restructuring, and succession planning of their business interests, including sales, ESOPs, and other exit strategies. Carmen also advises accounting professionals on the reporting of transactions and compliance with adequate disclosure requirements.

Carmen is an empathetic listener who endeavors to understand her clients’ singular perspectives to best design their legacy plan and further their goals for preserving family harmony, providing incentives for social responsibility and positive values, and addressing the financial and philanthropic education of their legacy recipients. Carmen’s high standards of commitment to her clients and years of experience enable her to pinpoint core issues, create alternative and innovative courses of action, and identify the best strategies and opportunities while simplifying complexity, identifying efficiencies, and motivating others to take action, all in a client-centric, collaborative, and tax-conscious manner.

Carmen is a Martindale Hubbell AV® Preeminent (5 out of 5) rated tax attorney for ethical standards and professional ability in the areas of legal knowledge, analytical capabilities, judgment, communication, and legal experience, based on evaluations by other attorneys and the judiciary in the United States.

Read more about Carmen Irizarry-DiazEmail
Show more Show less
  • Posted in:
    Tax
  • Blog:
    Legacy Advisors
  • Organization:
    Greenberg Traurig, LLP

Call us at 1-800-913-0988 or email sales@lexblog.com.

Facebook LinkedIn Twitter RSS
The Library at LexBlog
  • About LexBlog
  • The Field We Built
  • Library at LexBlog
  • Our Beliefs
  • Our Team
  • Contact LexBlog
  • Disclaimer
  • Editorial Policy
  • Terms of Service
  • Get Started
  • Publishing Solutions
  • Compass
  • Submit a Request
  • Support Center
  • System Status
Copyright © 2026, LexBlog, Inc. All Rights Reserved.
Law blog design & platform by LexBlog LexBlog Logo