

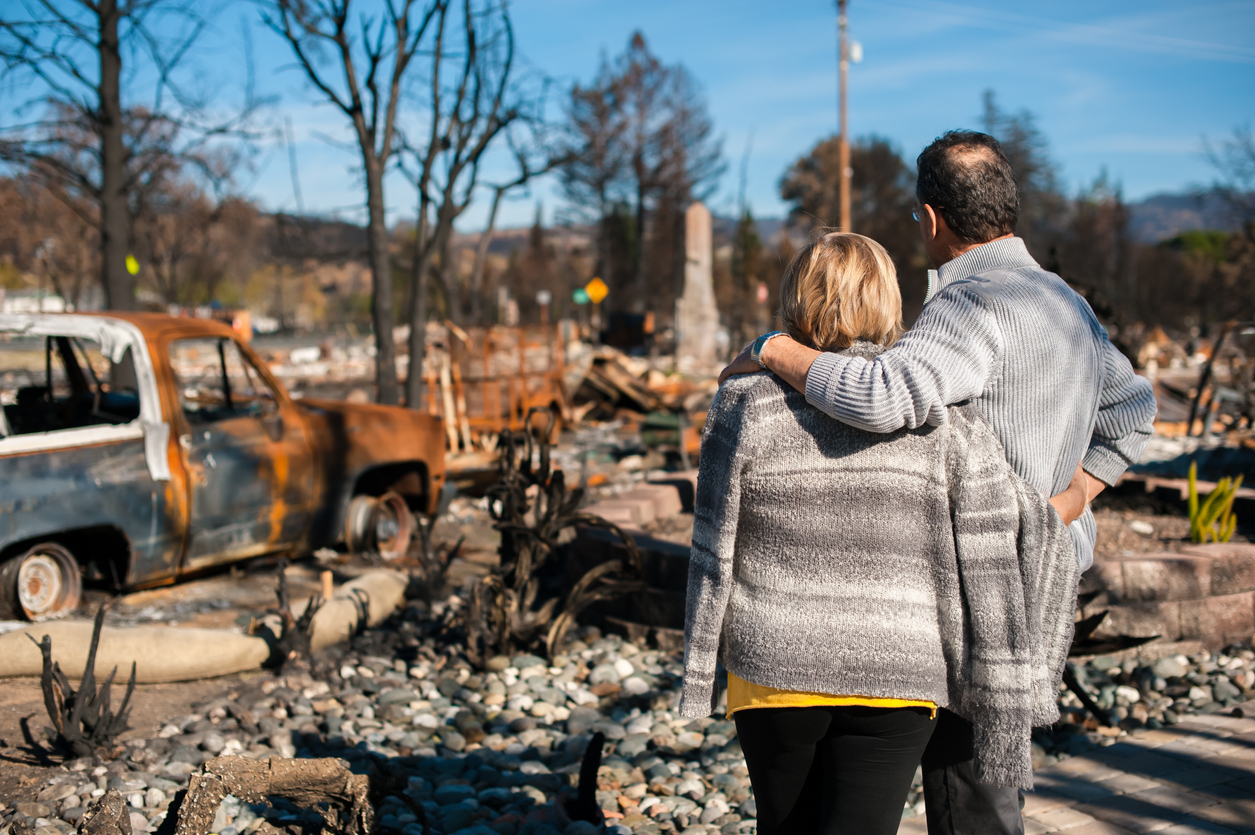
“If they do not ask, do not tell.” That is the culture of some insurance carriers when it comes to explaining all the benefits available under additional living expense provisions of an insurance policy. Some carriers simply do not train their property insurance adjusters on those policy benefits so that they are ignorant about how many benefits and options are available under the policy, which could otherwise benefit policyholders.
Additional Living Expenses (ALE) is the counterpart to business income and extra expense coverage under a commercial policy. What happens when a business burns down? The commercial policyholder is entitled to extra expenses at a temporary location that is similar to the fire-damaged business property so the business can maintain its operations. Many business owners then purchase a separate business property as the temporary location under a separate entity name and lease it to the insured business at a fair market value rate. The insurance company then pays to equip the temporary location. This is discussed in Business Income and Extra Expense – Understanding the Differences:
Generally, extra expense coverage provides coverage for necessary expenses incurred during the period of restoration that would not have been incurred without the loss. This coverage pays for the extra expenses incurred to avoid or minimize the suspension of business and to continue operations at the business premises described in the insurance policy or at a replacement premises or temporary location, including relocation expenses and costs to equip and operate the replacement premises.
Similarly, a burned down-home results in a policyholder needing a temporary location while the home is being rebuilt. The homeowners can do the same thing. They can purchase a temporary home; they should do this under a separate legal entity. Then, they should obtain fair rental value estimates of a similar furnished and unfurnished home, equivalent to the burnt one. Then, they should lease the temporary property back to themselves.
Commercial property insurance adjusters who are sophisticated and are trying to help the business owner and the insurance company reduce lost business income explain these options every day as part of their adjustment process. This is not the case regarding residential property insurance adjustment.
While it is important for homeowners to carefully read their policy for policy limits available under the policy and know their financial ability to purchase a temporary home, I have never heard any policyholder ever tell me that their residential property insurance adjuster explained this benefit and option to them.
Most of the time, the insurance companies are hoping that the residential policyholder will find the cheapest temporary housing. They do not tell the customers of the option because they do not save money, like in the commercial scenario when an insurer must pay for lost business income. It is an everything to lose and nothing to gain scenario by explaining these benefits.
Personal line carriers escape paying a great deal of additional living expense payments by not fully explaining options to their customers. There is a motivation to keep their residential property insurance adjusters ignorant.
Thought For The Day
Nothing strengthens authority so much as silence.
—Leonardo da Vinci