

Coverage for Damage to Vacant Dwelling Limited
Post number 5388
Vandalism Damage to Vacant Dwelling Excluded
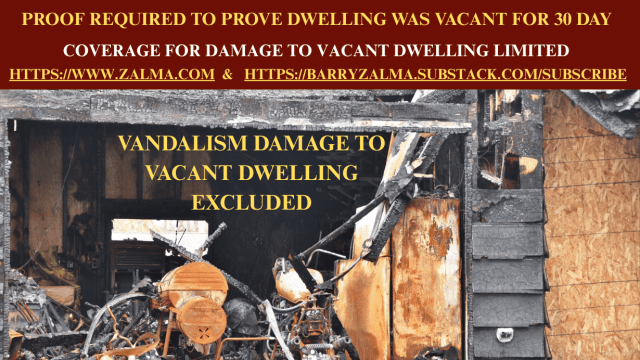
In Tyrone Williamson v. Farmers Insurance Co., 2026-Ohio-2530, C. A. No. 30717, Court of Appeals of Ohio, Second District, Montgomery (July 2, 2026) Tyrone Williamson owned a duplex in Dayton, Ohio that he rented as two separate units. While the units were unoccupied by tenants, break-ins occurred in February, March, and April 2024, causing damage to doors, windows, walls, plumbing, flooring, fencing, lighting, a ceiling fan, grass, and other parts of the property, and resulting in the theft of items including tools, generators, a power washer, an air-conditioning unit, car wheels, and a radio.
Farmers Insurance paid approximately $17,000 for some damage from the first break-in but denied other claimed losses, including additional property damage, stolen personal property, and lost rent.
The trial court granted summary judgment to Farmers Insurance on Williamson’s complaint.
FACTS
The first payment covered the damage to the garage door, five of the exterior doors, and two windows. Williamson testified he was asked what damages occurred at the property that were not covered by the $17,000 payment. Williamson stated that he was also seeking lost rent under the policy. He explained that he had not sought reimbursement for the air conditioner, tools, generators, radio, car wheels, and power washer because the insurance adjuster told him that these times were excluded from coverage under the insurance policy.
In seeking summary judgment on Williamson’s request for reimbursement for these damages, Farmers Insurance relied on the vacancy exclusion.
Because there remained a genuine issue of material fact as to whether the rental units were vacant for at least 30 consecutive days at the time of loss, the Court of Appeals must conclude that the trial court erred by granting summary judgment on Williamson’s complaint to the extent he sought reimbursement for these damages.
LAW:
Summary judgment is reviewed only when no genuine issue of material fact remains, the moving party is entitled to judgment as a matter of law, and reasonable minds could reach only one conclusion adverse to the nonmoving party. Insurance policies are interpreted under ordinary contract principles; clear language is enforced as written, ambiguous provisions are construed against the insurer and in favor of the insured, and exclusions apply only to losses clearly intended to be excluded.
DISCUSSION/ANALYSIS:
The appellate court held that a genuine issue of material fact existed as to whether the duplex was “vacant” under the policy. Although the parties focused on whether Williamson was constructing, altering, or repairing the property, the policy defined “vacant” as the absence of most furniture and other items needed for human occupancy.
The record did not establish, as a matter of law, that most such items were absent, and the policy did not define “items needed for human occupancy.” Because stoves and refrigerators arguably qualified as such items and were present, Farmers Insurance did not conclusively prove the vacancy exclusion barred coverage for dwelling-related damage.
The court held that the policy plainly excluded coverage for theft of personal property, including materials and supplies, and also barred lost-rent coverage because no tenants were renting the premises at the time of the losses.
CONCLUSION:
The court affirmed in part, reversed in part, and remanded the case to the trial court. Summary judgment was improper on Williamson’s claims for dwelling-related damage because factual questions remained about vacancy.
ZALMA OPINION
The Vacancy exclusion exists in almost every dwelling coverage because when a dwelling is left vacant the risk of loss is increased logarithmically. The language eliminates coverage after the dwelling is left vacant and not sufficient for human occupancy for 30 days. Since, on a motion, the insurer was unable to prove the vacancy exceeded 30 days the Court of Appeals sent the case back to the trial court to see if that defense could be proved. Insurance is a contract and Farmers proved some of its defenses and left available some parts of the loss not yet proved to be determined at trial or another motion for summary judgment.
(c) 2026 Barry Zalma & ClaimSchool, Inc.
Please tell your friends and colleagues about this blog and the videos and let them subscribe to the blog and the videos.
Subscribe to my substack at https://gbarryzalma.substack.com/subscribe
Go to X @bzalma; Go to Barry Zalma videos at Rumble.com at https://rumble.com/account/content?type=all; Go to Barry Zalma on YouTube- https://Cwww.youtube.com/channel/UCysiZklEtxZsSF9DfC0Expg; Go to the InsuranceClaims Library – https://lnkd.in/gwEYk.